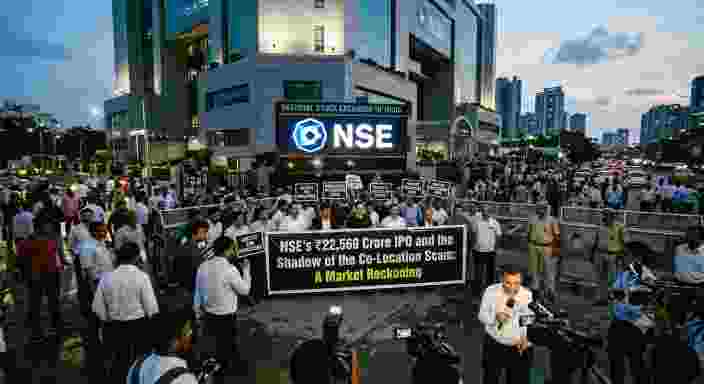
NSE’s ₹22,569 Crore IPO and the Shadow of the Co-Location Scam: A Market Reckoning
- Editor
- September 22, 2026
- Uncategorized
- 0 Comments
New Delhi, September 2026 — The National Stock Exchange (NSE) has officially closed its monumental public offering, registering a 5.69x over-subscription. While institutional investors piled in with a aggressive 12.68x subscription rate, retail participation remained notably reserved at 1.36x.
Behind the headline-grabbing numbers and solid profitability figures lies a complex corporate narrative: a decade-long regulatory standoff, an entirely Offer for Sale (OFS) structure, and the lingering ghost of India’s most infamous market scandal.
Selling Shares, Not Building Capital: The OFS Dilemma
For retail investors examining the prospectus, the mechanics of the IPO raised immediate questions. Because the entire issuance was structured as an Offer for Sale (OFS), existing institutional shareholders and early backers were the ones cashing out. Not a single rupee of fresh primary capital is entering the exchange’s balance sheet to fund new infrastructure or expansion.
Coupled with a valuation that left many conservative investors waiting on the sidelines, retail caution translated into a tepid 1.36x uptake—a stark contrast to the institutional frenzy. Market participants opted to adopt a “wait-and-watch” stance ahead of its scheduled debut on the Bombay Stock Exchange (BSE) on September 24.
The Co-Location Scandal: When Seconds Meant Millions
The hesitation surrounding the NSE is not born in a vacuum. For years, the exchange’s path to the public markets was entirely blocked by regulatory investigations tied to the 2015 co-location scam.
The mechanics of the scandal exposed a monumental vulnerability in market fairness:
- The Advantage of Time: Select high-frequency trading brokers gained unauthorized, advanced access to NSE’s server logs and tick-by-tick market data fractions of a second before the rest of the market.
- The Profit Play: Armed with a 10- to 30-second data advantage, favored entities could accurately predict price movements, executing trades ahead of retail investors and institutional funds.
- The Institutional Defense: While NSE management repeatedly framed the anomaly as a technical oversight rather than a malicious conspiracy, the fallout crippled investor trust and froze its public listing plans for nearly a decade.
It was only after prolonged legal battles and a substantial settlement with SEBI—including a massive financial penalty totaling nearly ₹1,500 crore—that the exchange finally cleared its regulatory runway.
A Profitable Giant with a Duopoly Moat
Despite its turbulent regulatory history, the NSE commands an indispensable position in the Indian financial architecture. Operating within a practical domestic duopoly alongside the BSE, the exchange generates robust revenues and substantial net profits.
Even as recent financial statements reflected minor profit and revenue corrections, the sheer volume of trades coursing through its servers ensures that the NSE remains a cash-generative powerhouse.
The Bottom Line
The NSE’s public debut is more than just a massive financial event; it is a test of institutional resilience. As the exchange prepares for its BSE listing, it leaves behind an era of opaque data leaks and protracted legal warfare. For retail investors, the core question is no longer about profitability, but whether the exchange has truly closed the door on its past to build a transparent, uncompromised future for India’s capital markets.