India’s Bank Deposits Hit 15-Year High at 17.8%: RBI Aggressively Steps in to Cool Liquidity
- Editor
- September 28, 2026
- Uncategorized
- 0 Comments
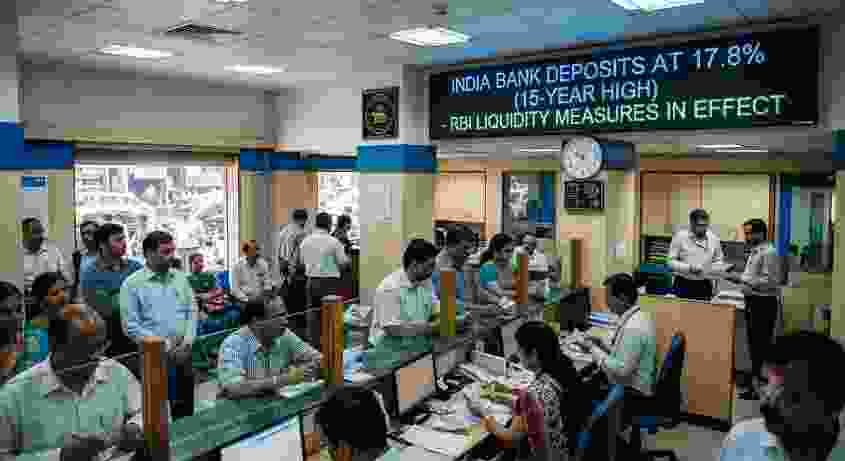
New Delhi, September 2026 – The Indian banking sector is experiencing a massive liquidity swing. Driven by aggressive mobilization and shifting macroeconomic currents, bank deposits surged by an eye-catching 17.8% year-on-year by the end of August, marking a 15-year high for deposit growth.
Concurrently, credit expansion stood firm at 19.1%, narrowing the once-alarming gap between credit and deposit growth down to a razor-thin 1.3 percentage points. But even as the banking ledger shows signs of stabilization, the Reserve Bank of India (RBI) is actively stepping in to tighten the screws, deploying tactical bond sales and specialized deposit windows to keep inflation on a tight leash.
Closing the Gap: Deposits Catch Up to Credit Demand
Not long ago, banking analysts sounded alarm bells over a dangerous structural imbalance: credit was expanding near 19% while deposits lagged behind at 12–13%, threatening to throw the financial system into a liquidity crunch.
The latest August data reveals a dramatic reversal. The gap has compressed from a perilous 5.5% down to just 1.3%.
- The NRI Factor: A major catalyst behind this deposit revival has been the RBI’s clever strategic maneuvering—specifically opening long-term FCNR(B) deposit windows for Non-Resident Indians (NRIs). By offering lucrative 3-to-5-year tenures backed by dollar-denominated currency assurances, the central bank successfully pulled substantial foreign capital back into domestic banking vaults.
The RBI’s Playbook: Sucking Liquidity Out Through Bond Sales
Despite healthy deposit inflows, the central bank is taking zero chances with excess money sloshing through the financial system. To preemptively combat inflationary pressures, the RBI has executed a series of aggressive liquidity-withdrawal operations.
In a staggered sequence through September, the central bank systematically pulled ₹100,000 crore out of the banking system via precise bond sales:
- ₹25,000 crore extracted on September 17.
- An additional ₹25,000 crore pulled on September 21.
- A further ₹25,000 crore scheduled for withdrawal by September 28.
How It Works: Under these operations, the RBI takes cash from commercial banks in exchange for government securities, paying banks an attractive 7% interest rate on these parked funds. While this cushions bank balance sheets, it deliberately restricts the amount of loose capital commercial banks have on hand to flood the market with cheap loans.
Are Interest Rates Heading Higher?
Financial experts note that the RBI’s aggressive liquidity management mirrors recommendations from recent research reports—such as those from SBI Research—advocating for higher repo rates to cool runaway demand.
By making wholesale funds more expensive and curbing easy retail credit access, the central bank is signaling a clear economic objective: slow down consumer spending, suppress aggregate demand, and keep inflation firmly anchored. If credit becomes harder and costlier to secure, household spending cools, taking the heat off consumer price indices.
Bottom Line
A 15-year high in bank deposits proves that public trust in domestic financial institutions remains exceptionally robust. However, the RBI’s aggressive liquidity-sapping measures show that the central bank is playing a long, cautious game. As the regulator actively drains billions from the banking network to manage inflation, both lenders and borrowers must prepare for an environment where cheap, frictionless credit may soon become a thing of the past.